Gold secures a contract; it does not define its compliance
Rahn refers to pledged collateral. When gold supports financing, the religious assessment must consider the underlying loan and every charge, not simply the presence of jewellery. Eisar’s published loan descriptions include a gold-backed arrangement, providing a specific cooperative example for further enquiry. Ask how the amount advanced is determined, whether custody or administration charges depend on actual services, and who reviews the contractual structure. Confirm the eligibility rules directly with the society. A conventional gold loan does not become an Islamic product merely because an advertisement substitutes Arabic terminology for its original description.
Protect the pledged property and understand enforcement
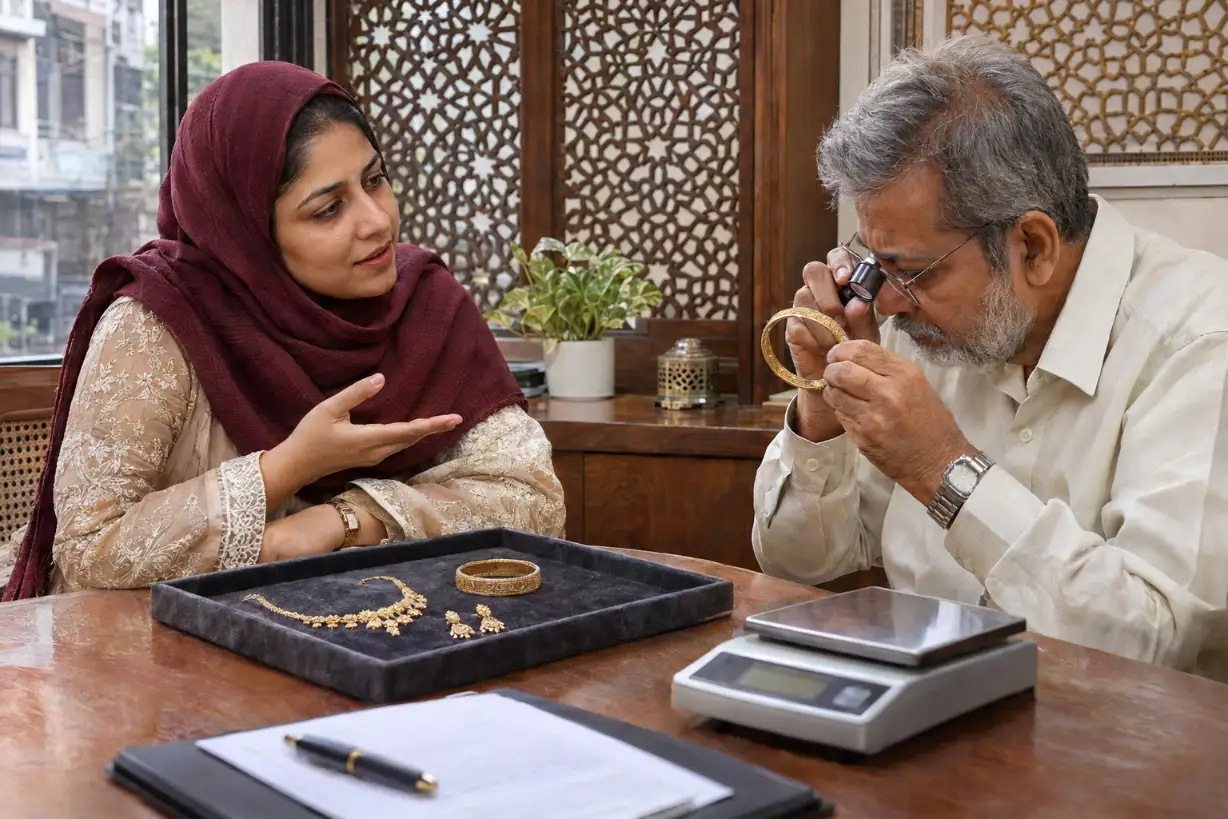
Arrange a written inventory recording the items, purity assessment, net gold weight and valuation method, and keep the acknowledgement safely. Clarify custody, insurance or other loss protection, the payment timetable and the steps for retrieving the jewellery after settlement. RBI’s gold and silver collateral directions address valuation, disclosures, release and auction safeguards for the regulated lenders within their scope. Do not assume an ordinary cooperative credit society falls into the same category as a licensed cooperative bank or NBFC. Before pledging, establish the rules applicable to that entity and the notice, costs and surplus-payment procedure if an auction becomes necessary.